Source of wealth and source of funds in investor onboarding
Distinguish source of wealth from source of funds in investor onboarding. Learn why identifying money origins matters for effective KYC compliance.
Source of wealth and source of funds in investor onboarding
Geoffrey Safar
October 05, 2026
“The money is coming from the investor's bank account” explains the last step of a transfer. It may tell the reviewer very little about the activity that generated the money.
That distinction matters when a family office subscribes to a fund through a company or trust. The person associated with the wealth, the entity making the investment and the account sending the payment can occupy different places in the structure. A reviewer needs an explanation that connects them.
The FCA distinguishes source of wealth, meaning how a customer or beneficial owner accumulated their overall wealth, from source of funds, meaning the origin of the money involved in the relationship or transaction, including the activity that generated it and its transfer route. The extent of the enquiry depends on the applicable obligations and risk.
The evidence request should identify the part of that explanation still missing: how the wealth arose, how it reached the subscriber or what generated this payment.
Wealth explains the history; funds explain this investment
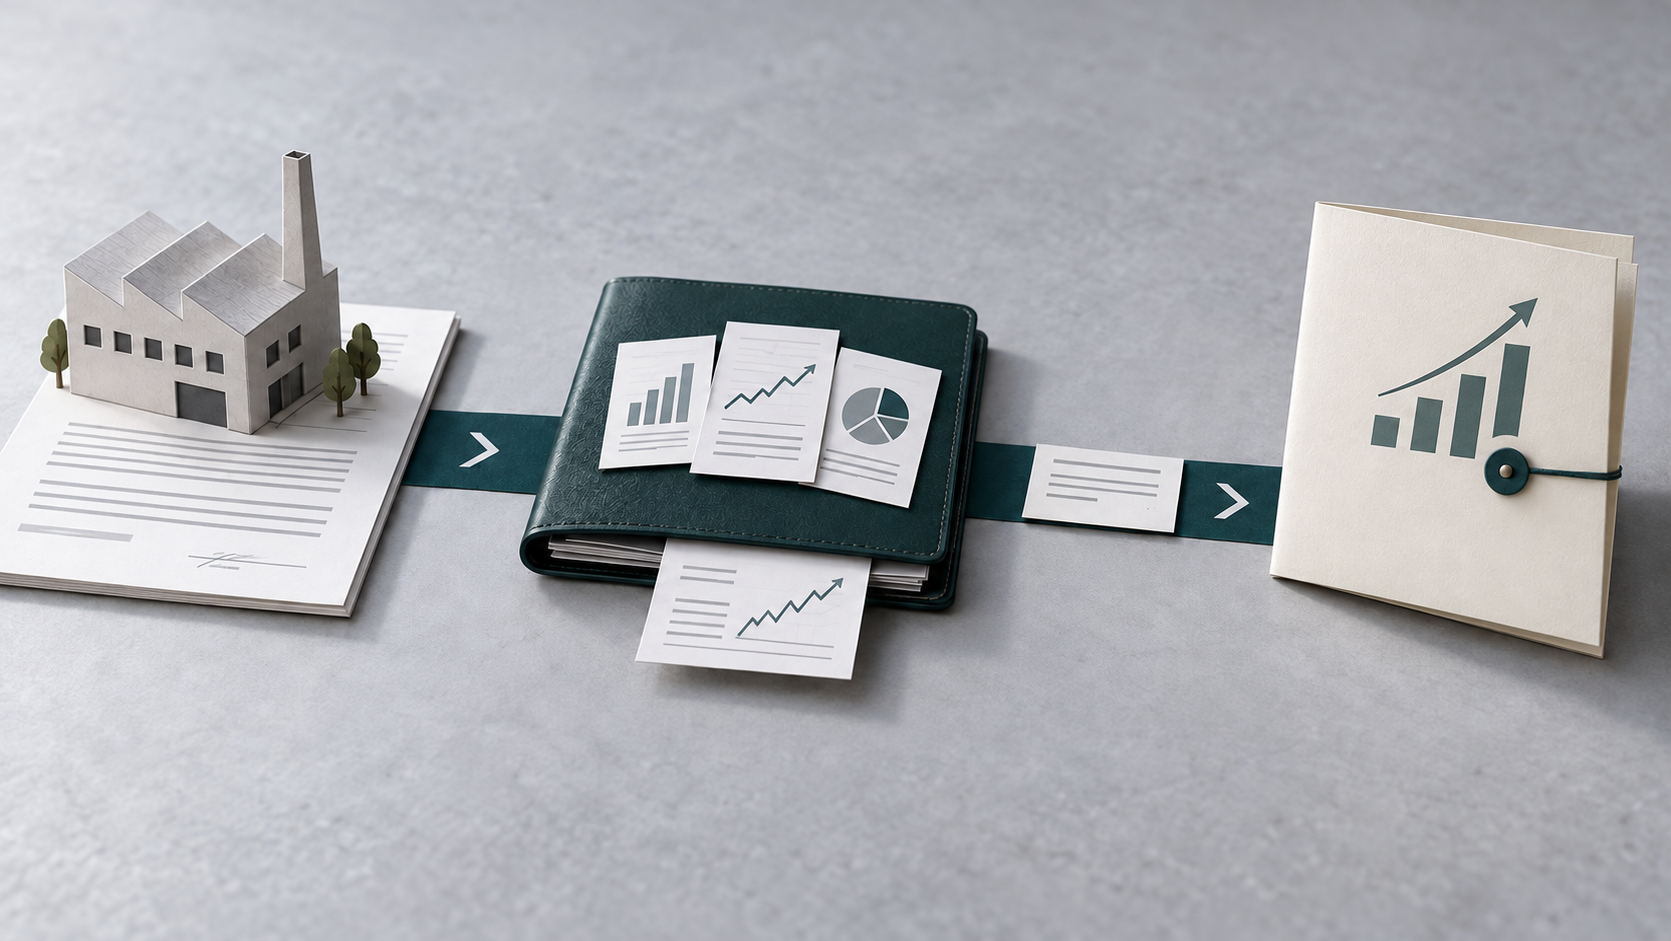
Consider a fictional family whose wealth originated in the sale of a manufacturing business. Years later, a family investment company subscribes to a private equity fund using proceeds from its investment portfolio.
The business sale helps explain the family's accumulated wealth. The portfolio disposal helps explain the particular subscription. Between those events, assets may have moved through family distributions, capital contributions and changes in legal ownership.
The evidence request should distinguish the history of the wealth from the funding of this subscription. They need enough reliable information to understand the relevant history and the present funding arrangement, with the depth of corroboration matched to the circumstances.
A sale agreement may establish that a transaction was agreed. Completion evidence may help establish that it occurred. Records identifying the seller and its ownership may connect the proceeds to the family. Evidence of subsequent contributions may explain how assets came to belong to the subscribing company.
The point is to understand what each document can support. A high transaction value on the first page of an agreement does not automatically establish how much a particular individual received, or that the subscribing entity now owns those proceeds.
Build the connection between the story and the subscriber
In the fictional example, the investor provides a short biography describing the founder's career, a press announcement about the company sale and a recent investment statement.
Those documents offer a starting point. The biography gives context. The announcement may corroborate the sale. The statement may show assets held at a particular date. The remaining question is how those facts connect to the legal entity making the commitment.
If the investment company received assets from a trust, the reviewer may need to understand that distribution and the authority behind it. If the subscription is financed through a loan, the explanation should identify that financing arrangement rather than presenting the payment as unencumbered sale proceeds.
This is why investor due diligence needs the investment context. The family's history and the subscribing entity's present funding both need explaining.
The reviewer should be able to write a short narrative connecting the origin of wealth, the relevant ownership changes and the present source of funds. Where that narrative jumps over an unsupported step, the gap becomes a focused request for evidence.
That request is also easier for the investor to understand. Asking for evidence of a specific distribution explains what the team is trying to establish and reduces the likelihood of receiving another general family biography.
Distinguish a weak explanation from an adverse conclusion
An incomplete explanation is a reason to enquire further. It is not, by itself, a finding of criminal activity.
Historical evidence may be difficult to obtain. A family business may have been sold long before records were routinely digitised. Wealth may have developed through several businesses, inheritance and reinvestment. The review needs to distinguish those practical difficulties from contradictions or an unwillingness to explain material facts.
In February 2020, FINMA found shortcomings at Julius Baer in understanding clients' wealth and the purpose and background of relationships, alongside other AML failures.
The operational lesson is to preserve the reasoning. If an explanation is accepted with corroboration from several sources, the record should show how those sources support it. If an important uncertainty remains, the decision should identify it explicitly and follow the firm's escalation process.
It also helps to separate facts from interpretation. “The statement shows receipt from Company A” is an observation. “This represents the documented distribution” is a conclusion that requires a connection to other evidence. Keeping that distinction visible makes the file easier to challenge and defend.
Make the assessment usable when the next payment arrives
The funding explanation gives the team a basis for comparing later payments with what was assessed at onboarding.
If the family investment company subsequently proposes to fund a drawdown through a new lender, the review can focus on that financing arrangement while retaining the established wealth history. The periodic review of the investor record should preserve evidence that remains relevant and update the parts affected by new facts.
This depends on communication between the manager, administrator and whichever team sees incoming funds. The people reviewing the payment need access to the approved explanation and a route for escalating departures from it. Otherwise, valuable analysis stays in the onboarding file while the live relationship develops elsewhere.
Steward's document-review and onboarding tasks support this evidence gathering. The reviewer can keep the business-sale records and subscription-funding evidence with the investor information, recording the reasoning for accepting the explanation or requesting more evidence.
The file should connect the business sale to the family's wealth, and the portfolio disposal to this subscription. A later payment from a new lender then has a clear point of comparison.
Related Insights
What should trigger a fresh look at an approved investor?
When approved investors change: triggering fresh KYC reviews without waiting for scheduled updates. Detect ownership shifts, funding changes and screening alerts.
What actually closes an AML remediation finding?
AML remediation findings require proof the underlying control works, not just task completion. Learn what regulators expect from effective remediation.
How sanctions evasion hides behind ordinary companies
Legitimate companies can mask sanctions evasion through shell networks and false invoices. Learn how to detect hidden payment purposes during investor onboarding.