Source of Wealth vs Source of Funds: For Private Banks
Distinguish source of funds from source of wealth in private banking. Learn why this critical gap is where money laundering thrives and how to properly document both.
Source of Wealth vs Source of Funds: For Private Banks
arik oslerne
September 05, 2026
Two questions sound almost identical and are constantly confused, including by people whose job is to know the difference.
Source of funds: where did this specific money come from?
Source of wealth: how did this person get rich?
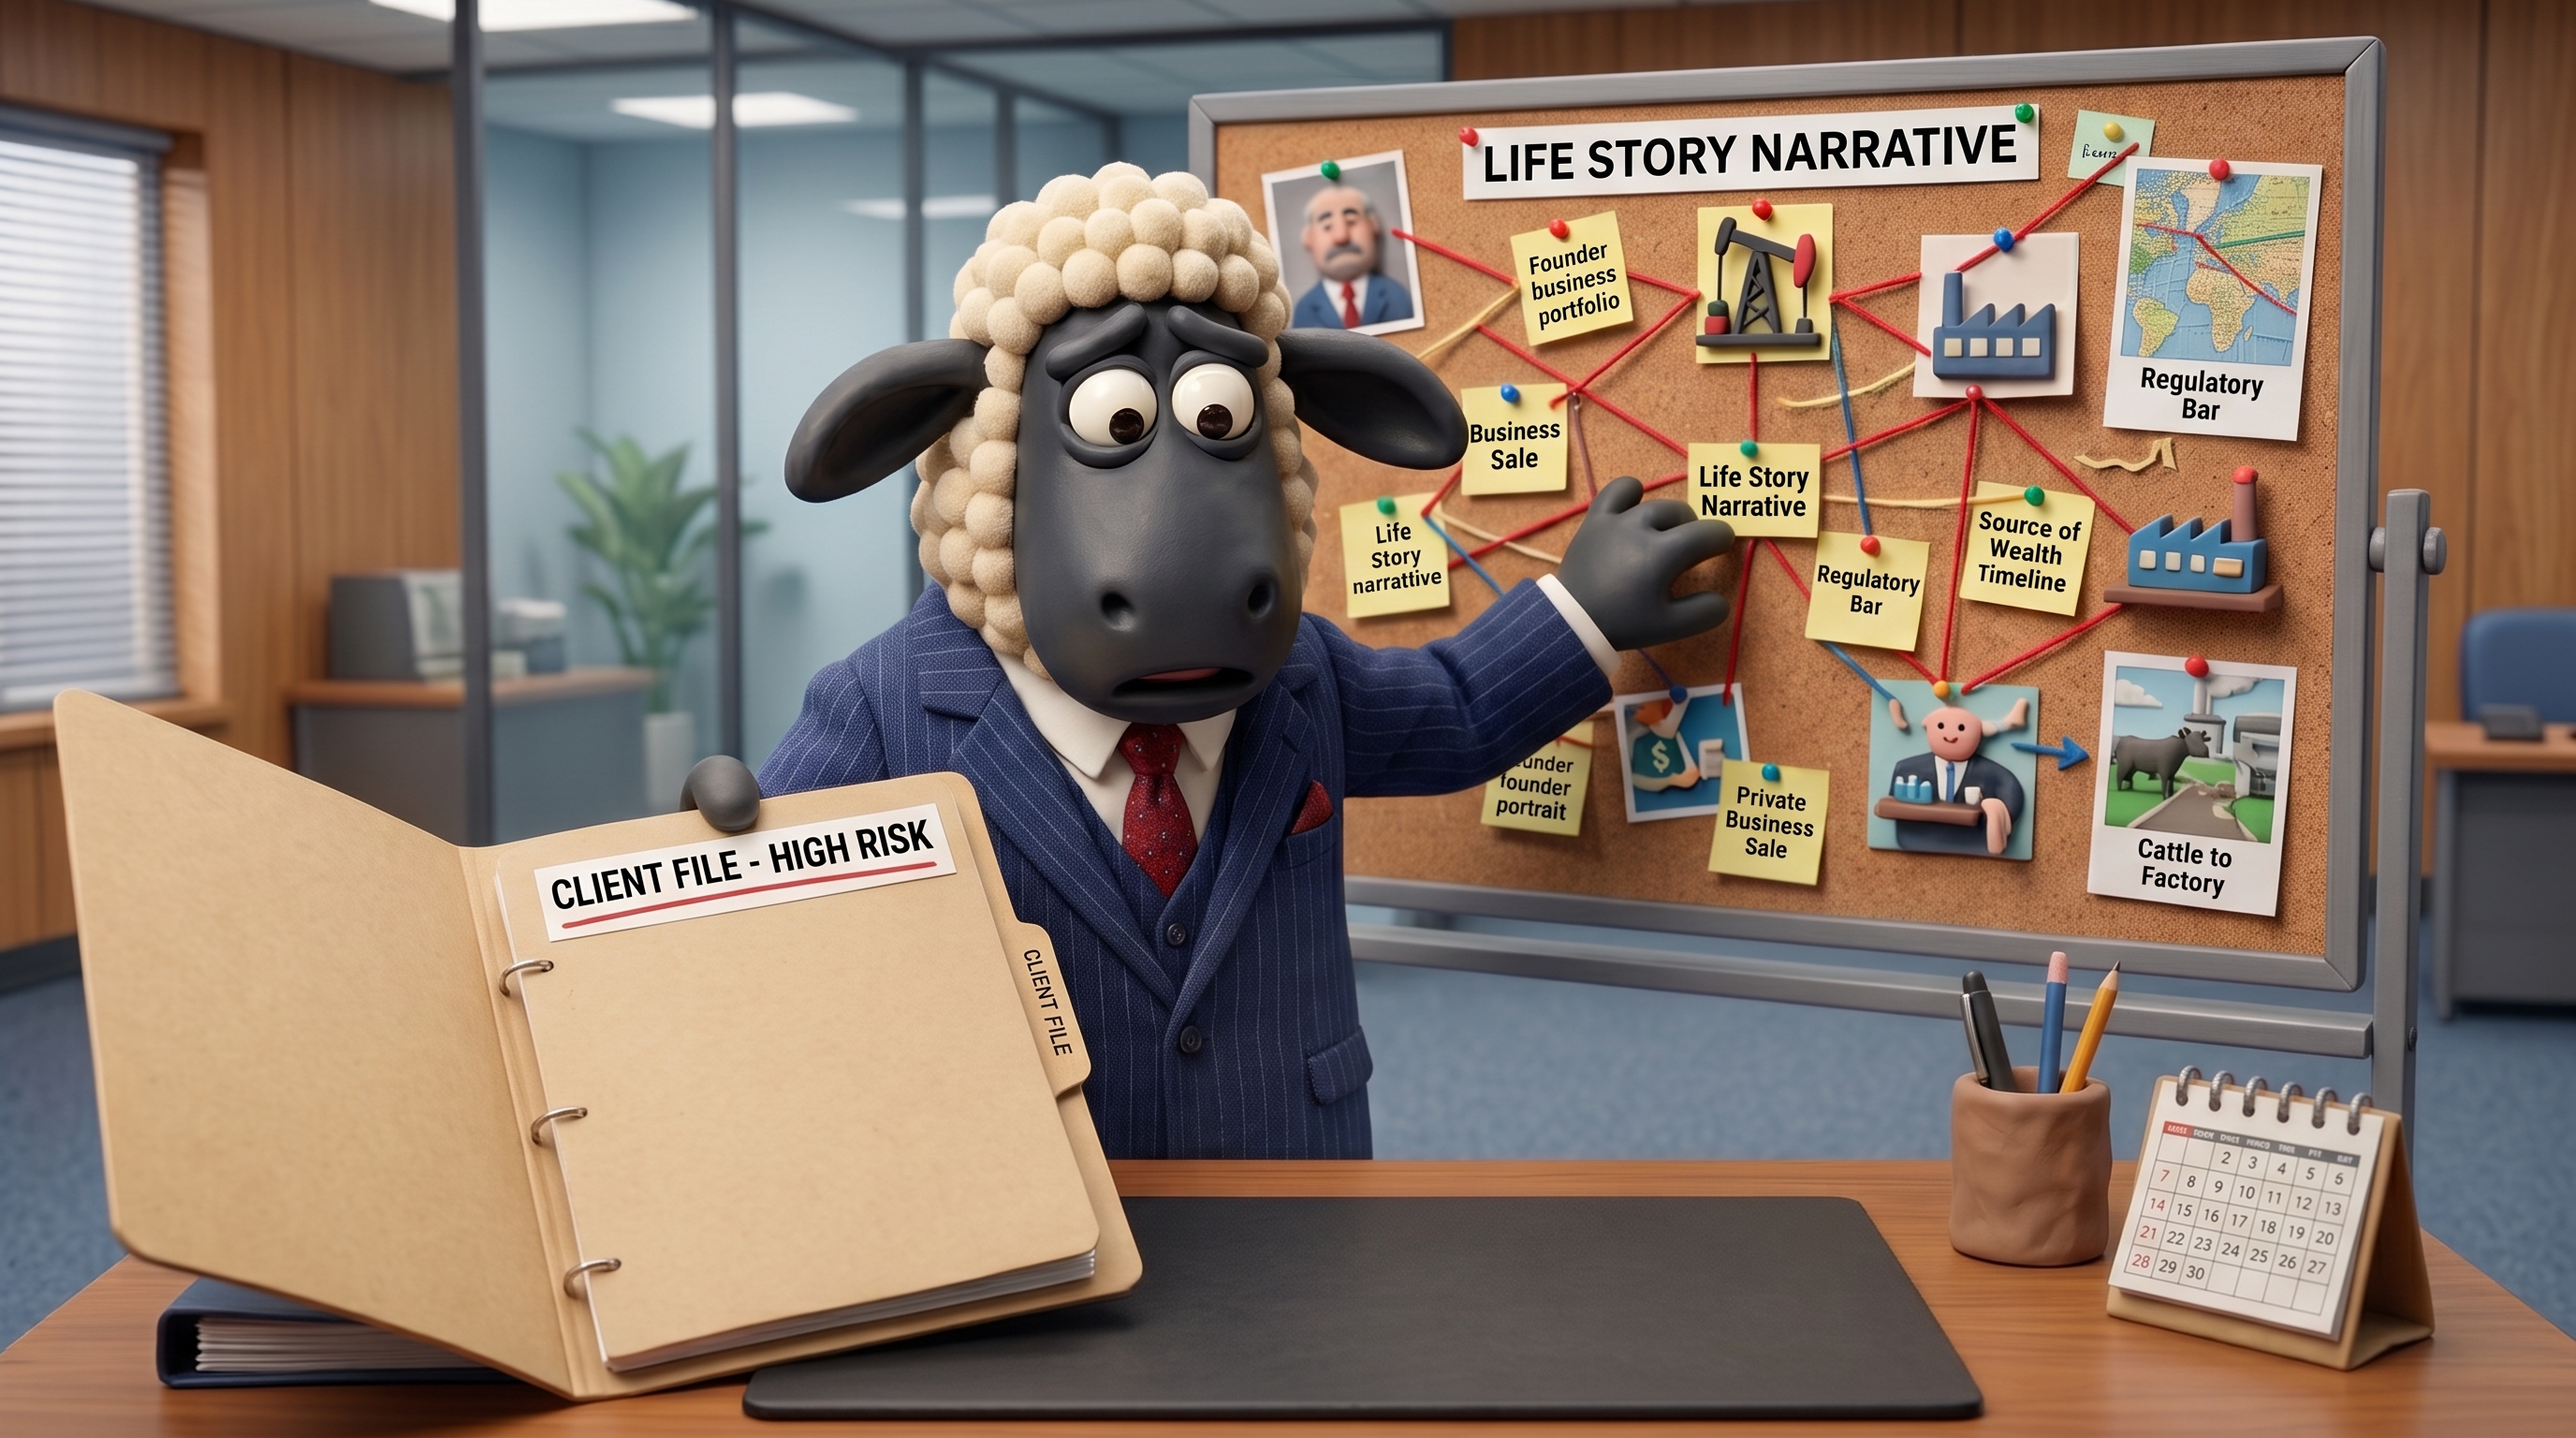
One is about a transaction. The other is about a life. And the gap between them is where a remarkable amount of money laundering lives, because it's entirely possible for the answer to the first question to be clean while the answer to the second is a fabrication. The wire came from a reputable bank account in the client's name. Fine. And how did forty million get into that account over a lifetime? Response - a one-line note reading "successful businessman."
Open a sample of private banking and fund files and you'll find that phrase, or its cousins - "family wealth," "proceeds of business activities," "investments" - doing load-bearing work in the highest-risk relationships on the book. This is the part of the file everyone hopes nobody asks about.
Why the distinction actually matters
Source of funds is a plumbing question. It's answerable with bank statements and transfer records, and it mostly gets answered, because the mechanics of payment force it into view.
Source of wealth is a narrative question, and narratives are where lies live. A laundering operation can generate impeccable plumbing: real accounts, real transfers, clean-looking hops through respectable institutions. What it cannot easily generate is a coherent life story where the wealth adds up: a career that plausibly produced the amounts, sales that actually happened, businesses that genuinely traded at the claimed scale.
That's why regulators keep raising the bar on SOW for high-risk and high-net-worth relationships, and why enhanced due diligence regimes treat it as central. The wealth story is the hardest thing to fake, but only if someone actually checks it.
Why files stay thin anyway
Three honest reasons:
Nobody wants to interrogate the client. Relationship managers live in terror of the awkward question. Asking a billionaire prospect to evidence how they made their first ten million feels, to the front office, like asking them to prove they're not a criminal - mid-pitch. So the question gets asked softly, answered vaguely, and recorded generously.
Corroboration is genuinely laborious. Verifying a wealth narrative means reading company filings from twenty years ago, checking whether the claimed business sale appears in registries or press, reconciling career timelines against the arithmetic of accumulation. Hours per file, across languages and jurisdictions. Compliance budgets rationed it; "risk-based" made the rationing respectable.
Plausibility gets mistaken for evidence. "Successful businessman" survives review because it's plausible, and plausible feels like verified when the reviewer has thirty files in the queue. But plausibility is exactly what a competent bad actor manufactures. The story is always plausible, but is it corroborated?
What a real SOW analysis looks like
The test is simple to state: does the wealth arithmetic work, and is each major step independently evidenced?
Take the claimed narrative - built a distribution business, sold it in 2011, invested the proceeds - and check each link. Does the company exist in the registry with this person as founder or major shareholder? Do its filed accounts suggest a business that could sell for the claimed figure? Is there any independent trace of the sale? Do the amounts, once you run the timeline forward through plausible returns, arrive at anything near the current wealth?
You're not seeking notarised proof of every dollar. You're checking whether the story survives contact with independent sources. Most fabricated narratives don't - they're plausible in summary and hollow in detail, because building verifiable corroboration across decades of registries and records is precisely the part fraudsters can't retrofit.
And note what this means for the SOF/SOW relationship: strong source-of-funds evidence proves nothing about source of wealth. The wire always comes from somewhere respectable. That's what the respectable somewhere is for.
The practical playbook
1. Separate the two questions in your files, structurally
If your file format has one "source of funds/wealth" field, you've already lost. Two questions, two evidence sections, two standards.
2. Scale scrutiny to the gap, not just the risk rating
The trigger for deep SOW work isn't only jurisdiction or PEP status. It's the gap between wealth and evidence. A modest inheritance with documents beats "entrepreneur, $200m" with none.
3. Corroborate before you converse
Most of a wealth narrative is checkable without asking the client anything - registries, filings, press archives, litigation records. Do that work first. It turns the awkward interrogation into one or two precise questions, which is better compliance and better client experience.
4. Ban the load-bearing vague phrase
"Successful businessman" is not a source of wealth. Institute a simple rule: every SOW summary must name specific businesses, events and amounts, each tied to a piece of evidence. What can't be specified can't be verified.
5. Re-run the arithmetic when the numbers move
A client whose activity suddenly implies wealth beyond the documented story is a monitoring event, not a renewal formality. SOW is a living analysis.
Where Steward fits
The reason SOW checking stayed thin was cost: corroborating a life story across decades of registries, filings and archives took analyst days that nobody budgeted. That constraint is gone. Steward's AI does the excavation - reads the file, extracts the narrative, checks every claim against independent sources, runs the arithmetic - and hands your team a corroborated story or a precise list of what doesn't add up.
Related Insights
What should trigger a fresh look at an approved investor?
When approved investors change: triggering fresh KYC reviews without waiting for scheduled updates. Detect ownership shifts, funding changes and screening alerts.
What actually closes an AML remediation finding?
AML remediation findings require proof the underlying control works, not just task completion. Learn what regulators expect from effective remediation.
Source of wealth and source of funds in investor onboarding
Distinguish source of wealth from source of funds in investor onboarding. Learn why identifying money origins matters for effective KYC compliance.